 Login
 Register

What a Short Sale File Actually Starts With — and Why It’s Shorter Than You Think
Posted on 05. Oct, 2026 by ctlms in Blog, My Blog, Short Sale, foreclosure
“What does my seller actually have to give you to get this started?” I get that question from agents the minute a file is referred, and it usually comes with a worried tone, because most agents have been burned by a short sale that started with a three-inch stack of paperwork and a seller who stopped returning calls halfway through. So here’s exactly what a file at my office starts with. It’s six things, and it’s shorter than you’d expect on purpose.
What are the six things?
I send the seller one email with the documents attached, and here’s what’s in it.
- The authorization to release information. This gives the lender permission to speak with us about the account. Without it they will not discuss a short sale with us, period. We need one for each lender or lien on the property, so a first and a second mortgage means two signed copies, and a judgment or a home equity line means another. This is the one that matters first, because nothing else can move until it’s on file.
- A basic income and expense form. It’s a plain worksheet: monthly income for each borrower, what the seller owns, and what goes out each month. Nothing fancy. We ask the seller to fill it out as clearly and completely as they can.
- A hardship letter. In the seller’s own words, what happened that made the mortgage unaffordable, and what has changed since. Servicers want to see it, and it has to be true and it has to be theirs.
- The debt negotiation agreement. This is the three-page disclosure Connecticut requires. It spells out what we offer to do, and it’s blunt about the possible results: nobody can guarantee the lender will approve a short sale, a short sale can hurt the seller’s credit, and the seller has three business days to cancel. I’d rather the seller read all of that on day one than be surprised by it in month four.
- The short sale questionnaire. This one is the sleeper, and I’ll explain why in a minute.
- A copy of the mortgage statement. Plus whatever the seller has on any other liens.
One more thing that surprises people: everything has to be ink signed. No electronic signatures. Mailed copies should be copies, not originals.
Why only six? Where are the pay stubs and bank statements?
They come later, and that’s deliberate. Here’s the WHY.
Before the authorization is on file, I don’t know anything useful about the loan. Once the lender has it, we find out who actually owns the loan, whether it’s government insured, whether there’s mortgage insurance, and what documents that particular servicer wants to see from the seller along with the offer. Who owns the loan is the first thing you need to know on any short sale, and every investor has different requirements. Collecting a generic pile of documents before we know what this lender wants is how you end up collecting the wrong pile.
And then there’s the clock. Fannie Mae’s servicing guide says income documents can be no more than 90 days old as of the date the servicer first determines the package is complete. A short sale runs four to six months from start to close, with lender approval alone commonly taking 60 to 120 days. So if you have the seller gather pay stubs and bank statements in week one, there’s a real chance you’ll be asking for them again in month three. Nobody enjoys asking a stressed-out homeowner for the same paperwork twice, and homeowners who get asked twice have a way of going quiet.
Why does the questionnaire matter so much?
Because it’s where the file-killers show up early. It asks who the other lienholders are, whether there’s an HOA and whether the dues are current, whether water, sewer or town services are behind, whether the property is owner-occupied, rented or vacant, and whether the seller has ever filed bankruptcy or is planning to. It asks about military service. It asks about other real estate. Every one of those answers changes how the file gets handled.
A second mortgage nobody mentioned, HOA arrears, a bankruptcy where the liens weren’t dealt with. Those are the things that stall a closing, and the question is only whether you hear about them on day one or from the closing attorney the week before the closing date. I know which one I prefer. The questionnaire also asks whether the seller has their own real estate attorney with short sale experience, so we aren’t scrambling for one when it’s time to close.
What if the owner has passed away?
Same package, with a few additions. The estate sends a copy of the death certificate, a copy of the fiduciary certificate, and a same name affidavit for the fiduciary, which is what lets the bank accept the fiduciary’s signature on the documents. Everything else on the list stays the same.
Does a complete package mean the lender approves?
No, and I’d be lying if I let you leave with that impression. A complete starting package gets the file opened and moving. After that the lender decides whether to approve it, based on the value of the property, the offer, the investor’s guidelines, and the seller’s hardship and finances. The lender has the final say. That’s what the state-required agreement tells the seller, and it’s what I tell you.
The takeaway
A short sale file starts with six documents: the authorization, an income and expense form, a hardship letter, the debt negotiation agreement, the questionnaire, and a mortgage statement. Get them back signed in ink, and you’ve done the part you can control. The rest of the package gets built to that lender’s specific requirements once we know what they are, which keeps the income paperwork from going stale while the file waits its turn.
Send me the address and the approximate payoff. I’ll tell you within a day whether it’s worth pursuing.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Credit After a Short Sale — The Honest Comparison to Foreclosure
Posted on 28. Sep, 2026 by ctlms in Blog, My Blog, Short Sale, foreclosure
“Doesn’t a short sale look better on my seller’s credit than a foreclosure?” I get some version of this question from listing agents and attorneys almost every time a file gets referred to me, usually because the seller asked them first and they want to give a good answer. It’s a fair question. I wish I could just say yes. The honest answer is closer, and a lot more useful, than that.
Do credit scores actually treat a short sale differently than a foreclosure?
Not the way most people assume. A credit scoring model doesn’t have a category called “short sale” and a separate one called “foreclosure.” It scores what actually gets reported to the credit bureau about the account: paid as agreed, settled for less than the full balance, charged off, ninety-plus days late, and so on. A short sale and a foreclosure usually get reported as some version of “not paid in full,” coming off what was probably a clean payment history before the trouble started. The label on the closing paperwork doesn’t change what the algorithm sees. What changes the score is the derogatory mark itself.
So how big is the hit, really?
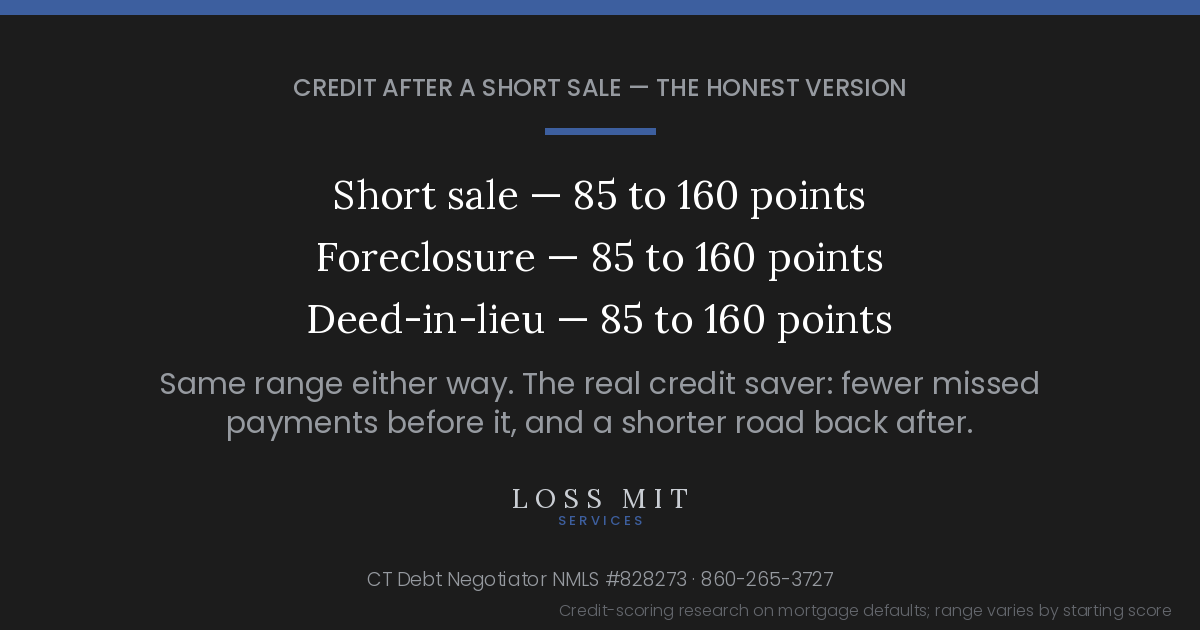
Bigger than most sellers expect, and close to the same either way. Credit-scoring research on mortgage defaults puts the drop at roughly 85 to 160 points, and that range applies whether the account closes as a short sale, a foreclosure, or a deed-in-lieu. Where you land in that range depends mostly on where you started. A seller sitting at 780 loses more, in raw points, than a seller sitting at 640 — the higher the score, the more room it has to fall. I tell every referring agent this up front, because the seller is going to hear it from someone eventually, and I’d rather it be on day one than from a lender six months from now.
Where does the real credit saving come from?
Here’s the part nobody explains to the homeowner, and it’s the whole reason the timing of the referral matters more than anything I do on the file once I have it.
The short sale itself is one derogatory entry. Every missed mortgage payment leading up to it is another one. Thirty days late gets reported. Sixty days late gets reported. Ninety, a hundred and twenty, each one is its own mark on the report, and each one stacks on top of the last. By the time a seller has ridden it out for a year and then finally calls somebody, the short sale is landing on top of twelve months of lates, and the score at the end reflects all of it.
Now compare that to the seller who gets a file to me while they’re still current, or one payment behind. The short sale still hurts. It still lands somewhere in that 85 to 160 range. But it’s landing on a clean history instead of a year of missed payments, and the score at the end is in a completely different place. Same short sale, very different result. The fewer missed payments on the report, the smaller the total hit.
That is the honest version of “a short sale is better for your credit.” It isn’t better because of what it’s called. It’s better because a seller who deals with it early takes one hit instead of thirteen. Being proactive is the credit saver. The short sale is just the vehicle.
What about qualifying for a mortgage again?
This is the second real advantage, and it points in exactly the same direction.
- Fannie Mae cuts the wait roughly in half. A conventional buyer needs 7 years after a foreclosure to qualify again, or 3 years with documented extenuating circumstances. After a short sale, that number drops to 4 years standard, or 2 years with extenuating circumstances. Same credit hit, half the wait.
- FHA is 3 years after either one. FHA doesn’t distinguish much between a short sale and a foreclosure on the standard timeline — both are a 3-year wait.
- FHA has a zero-wait path, and it rewards the proactive seller. If your seller’s mortgage payments and every other monthly debt — credit cards, car loan, student loans, all of it — were current for the full 12 months before the short sale closes, FHA doesn’t require any waiting period at all. That’s a real advantage, and it’s the one most agents have never heard of. Notice who qualifies for it: the seller who stayed current. The same seller who took the smaller credit hit.
The advice that costs your seller both
Here’s where I have to say the uncomfortable thing out loud, because I see this go wrong. Somewhere along the way, somebody tells the homeowner to stop making the mortgage payment during the short sale process — sometimes it’s framed as “it’ll make the file move faster,” sometimes as “you won’t need the money anyway once it closes.” Every missed payment that follows is another mark on the report, and the first one takes the FHA zero-wait path off the table. Nobody explains that trade to the seller at the time. I do, every time it comes up, because it’s the difference between your seller buying again next year and your seller buying again in three, with a lower score when they get there.
[story — a referred file where the seller had been told to stop paying months before it reached me, and what that cost them on both the score and the zero-wait path. Fill in or delete before publishing.]
One more thing that moves the needle
Whether the file closes with a deficiency balance or without one. A short sale negotiated to a full release, with no money still owed on paper, tends to land a little softer than one that reports a balance still outstanding. That’s one more reason how a short sale gets negotiated matters, not just that it happened instead of a foreclosure.
The takeaway
A short sale does not spare your seller’s credit the way the old sales pitch claims. The score drop lands in roughly the same range as a foreclosure — 85 to 160 points, worse for higher starting scores — and anyone telling a seller otherwise is setting them up for a bad surprise later. What actually limits the damage is getting there early: fewer missed payments before the short sale means a smaller total hit, and it keeps the FHA zero-wait path and the shorter Fannie Mae timeline in play. That’s the pitch that holds up, because it’s the true one.
Tell your seller the real version. A short sale isn’t a credit-repair strategy. Getting the file to me early is the closest thing to one.
Send me the address and the approximate payoff. I’ll tell you within a day whether it’s worth pursuing, and what the road back looks like for that seller’s loan type.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Commission on a Short Sale — What Lenders Allow, and How the Reduction Actually Gets Negotiated
Posted on 21. Sep, 2026 by ctlms in Blog, Foreclosures, My Blog, News, Real Estate, Short Sale, foreclosure
“Am I actually going to get paid on this?” I get that question from agents all the time, usually about two minutes into the first phone call about a short sale listing, and I’d much rather you ask me on day one than find out the answer on the settlement statement in month five. So this post is the honest version, the one you’d get if you called me.
Do lenders cut commissions on short sales?
Yes. Not always, and not nearly as often as the 2009-era horror stories would have you believe, but it happens, and anyone who tells you it never happens is selling you something. What I want to do here is explain WHY it happens, because once you understand the why, you know exactly when to worry and when not to.
Start with who’s paying you. On a normal sale the seller pays the commission out of their equity. On a short sale there is no equity. Every dollar on that settlement statement, your commission included, comes out of the net that goes back to the investor who owns the loan, and that investor is already taking a loss. The banks don’t do short sales to help people, they do short sales to help themselves, and “help themselves” means recovering more than they’d expect to recover by foreclosing. So they have rules for what they’ll allow to come off the top, and the rules depend on who owns the loan. Who owns the loan is the first thing you need to know on any short sale, and this is one more reason why.
What do the big investors actually allow?
Here’s where the real numbers live, and they’re better than most agents expect.
1. Fannie Mae. The Fannie Mae Servicing Guide (section D2-3.3-01, if you want to look it up) lists the transaction costs a servicer can deduct from the sale price on a Fannie Mae short sale. Real estate commission is on the list, described as “customary for the market,” capped at 6% of the sales price.
2. Freddie Mac. Freddie put out a bulletin back in August of 2009 telling its servicers they could no longer condition approval of a short sale on cutting the listing broker’s commission, as long as that commission was 6% or under. Above 6%, the servicer is required to renegotiate it down to 6%. That rule has been the practice on Freddie files ever since.
3. FHA. HUD’s pre-foreclosure sale program, which is what an FHA short sale is called, allows a real estate commission of up to 6% as well.
So on the three biggest buckets of loans in Connecticut, a market-rate commission is an allowable cost and, in my experience, it usually survives the approval intact. That’s the good news, and it’s the part the 2009 stories leave out.
Where do the cuts really happen?
Three places, and after more than 2,000 of these I can tell you they’re pretty predictable.
1. Portfolio lenders and private investors. A local bank or credit union that kept the loan on its own books, or a private investor who bought the note at a discount, doesn’t have to follow anybody’s guide. Their “guideline” is whatever the person reviewing the file thinks is reasonable that day. Some are perfectly fair. Some see the commission as the easiest number on the page to trim. You don’t know until you ask, and I ask early.
2. Second mortgages and other junior liens. This is the big one. The second mortgage holder is often being asked to release a five- or six-figure lien for a few thousand dollars, and they know it. They can’t do much about the first mortgage’s payoff. They can’t do much about the taxes. So when they go looking for a place to squeeze, they look at the commission. It’s not personal. It’s just the only line on the statement they think they can move.
3. Any file where the net comes back a little short. This is the one that catches agents off guard. The valuation comes in, the investor runs the numbers, and the offer nets them a few thousand dollars less than their minimum. Somebody has to give. The buyer might come up a little. The seller, by definition, has no money to bring. So the negotiator on the lender’s side looks down the settlement statement and lands on the commission. This is the moment I’m talking about when I say I’ll tell you it’s coming before it comes. A good negotiator sees the net gap when the valuation lands, not when the approval letter shows up.
What changed with the buyer-agent side?
Since the NAR settlement took effect in August of 2024, buyer-broker compensation isn’t offered through the MLS the way it used to be. A lot of agents ask me how that plays on a short sale. The honest answer is that from the lender’s chair, nothing changed. The lender approves what’s on the settlement statement. If the seller is paying a buyer-broker fee, it shows up as a seller-paid cost, and the lender is looking at the total that comes off the top, however it’s split between the two sides. Write it up cleanly, put it where it belongs, and the total is what gets measured against the ceiling.
So here is the question to ask any short sale negotiator, licensed or not, before you refer a client: how exactly do you get paid, and where on the settlement statement does it land? A straight answer to that question is worth more than any promise about approval rates.
One settlement statement
I’ll say this every time commission comes up, because it’s the whole reason a commission can turn into a surprise. Every lienholder on the file gets the same settlement statement with the same numbers. The first mortgage, the second, the HOA, the tax collector, the town. If the first sees one commission figure and the second sees another, you don’t have a short sale, you have a problem that will surface at the worst possible moment. Same numbers to everybody, one statement, is how we run every file, and it’s how your commission stays what it was approved to be.
The takeaway
Lenders do cut commissions on short sales, but not randomly. On Fannie Mae, Freddie Mac and FHA loans, a commission up to 6% is an allowable cost and usually survives. The cuts come from portfolio lenders, junior liens, and files where the net comes up short, and all three of those are visible early to someone who’s looking. Know who owns the loan. Ask your negotiator how they get paid. Insist on one settlement statement. Do those three things and commission stops being the thing you find out about last.
Send me the address, the approximate payoff, and who services the loan. I’ll tell you within a day whether it’s worth pursuing, and what the commission picture usually looks like on that kind of loan.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Connect with Us


Bio
Sean Wilder started in the pre-foreclosure business in 2007. Previously he enjoyed successbusiness in the transportation industry, real estate investing and as a licensed Realtor. Sean brought the same determination and work ethic that lead to great success in his previous businesses to Loss Mit Services based in East Windsor, CT. His focus, combined with his drive to succeed, have been essential to his success as one of the area's top short sale negotiators.
Known for finding creative ways to overcome hurdles and never ending persistence; Sean, believes in the power of team. Sean and his team are in the trenches everyday, plowing through challenges and objections while negotiating with various lenders, and finding solutions to difficult problems. It is this daily experience that brings Loss Mit Services consistent success and provides them the knowledge to share.
Sean belongs to a number of industry groups and associations that allow him to collaborate, share, learn, teach and stay updated on the latest changes in the pre-foreclosure industry at the federal, state, local and lender specific levels.
Effective Oct 1, 2009 all debt negotiation companies that offer loan modification, short sale, or foreclosure rescue services needed to be licensed by the CT Dept of Banking. Sean and his company Loss Mit Services were the 1st to be awarded the Debt Negotiation License NMLS # 828273 which can be verified at the CT Dept of Banking Website by Clicking Here. In addition, effective Oct 1, 2011 Debt Negotiators were required to also be licensed Mortgage Loan originators and Sean also has received this license, NMLS# LO-831853.

Recent Comments