 Login
 Register

The Short Sale Valuation — How the Lender Decides What Your Listing Is Worth
Posted on 25. Aug, 2026 by ctlms in Blog
Agents ask me this one all the time: "The bank countered $40,000 above our offer — where did they even get that number?" The answer is the lender's valuation. And if you understand how that one document gets created, you understand more about short sale negotiation than most agents ever will.
But first I need to clear something up, because most of the short sale advice floating around is still working off the 2008-era playbook.
Is it a BPO or an appraisal?
If you took a short sale class ten or fifteen years ago, you were taught to expect "the BPO" — a Broker Price Opinion, where the lender pays a local agent a small fee to drive out, pull a few comps, and fill out a form. That was the standard back then, and honestly it was a big part of what made valuations such a fight — a rushed opinion from an agent who may have never worked the street.
Times have changed. These days lenders more often order full appraisals. FHA, VA, and USDA all require an appraisal on their short sale programs — on an FHA pre-foreclosure sale, the appraisal is baked into the program itself, and a VA compromise sale runs on a VA appraisal of value. On conventional files, Fannie Mae and Freddie Mac typically order appraisals as well. You'll still see BPOs on some files — junior liens especially, where the second-mortgage holder isn't going to pay appraisal money to value a lien it may collect pennies on — but if you're waiting for "the BPO agent" to show up on your listing, more often than not the person knocking is a licensed appraiser.
Does that make the valuation better? Usually, yes — an appraiser is licensed, works to a standard, and spends more than twenty minutes on it. Does it make your job at the appointment any less important? Not even a little.
Why does the lender order its own valuation at all?
Because they don't take anybody's word for what the house is worth. Not yours, not mine, not the buyer's, and definitely not the seller's. The lender is running a math problem: what do we net if we approve this short sale today, versus what do we net if we foreclose, take the property back, hold it, and sell it ourselves? The banks don't order valuations to help anybody — they order them to protect their own recovery. Once that report comes back, it becomes the lender's version of the truth. Every offer, every counter, every net sheet on the file gets measured against it.
So what do you hand the person who shows up?
Here's the part that hasn't changed in twenty years. The visit is short. The appraiser or agent doing it may not know the street, may not know the house's history, and can only work with what they can see and find. What you put in their hands matters.
One thing to be clear about first: an appraiser is independent. You can't negotiate with them, you can't pressure them, and you shouldn't try — that independence is the whole point of the system, and leaning on an appraiser is how agents get themselves in trouble. But appraisers can consider relevant information, and providing it is completely fair game. There's a real difference between arguing for a number and documenting the facts that support one.
So be at the appointment, and bring a package:
1. Your comps. Closed sales, recent, genuinely comparable — same style, same condition class, same part of town. If a comp needs a paragraph of explanation to make sense, write the paragraph. Whoever fills out that report has to build a comp grid either way; make it easy to build it with the right ones.
2. Condition photos. Every deficiency, documented. The wet basement, the roof, the 1970s electrical panel. Even a careful appraiser moving through a house once can miss things the seller has lived with for years.
3. Repair estimates from a licensed contractor, itemized, on letterhead. "Needs work" is an adjective. A written estimate is evidence. If the repairs are significant, more than one bid is better.
4. The listing history. Days on market, every price reduction, and the showing feedback — especially the buyers who walked and why. Nothing tells the value story like the market already having voted.
Notice what's not in that package: spin. We hand over documented facts, and they're the same facts we give every party on the file — the lender, the buyer's side, everybody. One version of the truth. That's not just the compliant way to run a short sale, it's the effective way, because a valuation done with real information in hand beats one done guessing alone in an empty house.
What if the number still comes in wrong?
It happens — we see it literally every day, and a high valuation kills more short sales than a low offer ever will. The good news is most servicers have a value dispute process. What moves a dispute is the same material as above: better comps, real repair bids, photos, and a clear explanation of why the contract price reflects the actual market. What does not move a dispute is adjectives — "the market is soft," "the house needs everything." Evidence or nothing.
And a caution: nobody can promise a dispute wins. Anyone who guarantees they'll "get the value fixed" is telling you something they can't know.
The takeaway
The valuation is where a short sale is usually won or lost, and these days it's usually a full appraisal — not the drive-by BPO the old classes taught you to expect. Find out when the appointment is, be there, and hand over a documented package: comps, photos, contractor estimates, listing history. Facts, not spin, and the same facts to everyone. That's the whole play.
If you're working a listing where the value question is going to decide everything, send me the address and the approximate payoff. I'll tell you within a day whether it's worth pursuing.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Only Three Companies in Connecticut Are Licensed to Negotiate Short Sales — Is Your Negotiator One of Them?
Posted on 23. Aug, 2026 by ctlms in Blog, Foreclosures, My Blog, News, Real Estate, Short Sale, foreclosure
I get this question from agents all the time: “Sean, does it really matter who negotiates the short sale? My seller found a company online.” The answer is... it matters more than almost anything else on the file, and here’s a number that should tell you why.
There are three companies in Connecticut licensed to negotiate a short sale on a homeowner’s behalf. Three. In the entire state.
And no, I’m not saying that from memory. I pulled the Department of Banking’s licensee list before writing this. One of the three is a national nonprofit housing counseling agency. Mine is one of the other two.
So what does the law actually say?
Simply put: in Connecticut, negotiating a short sale for a homeowner is “debt negotiation,” and debt negotiation requires a license.
That’s not my interpretation — it’s the plain text. Conn. Gen. Stat. Section 36a-671 defines “debt negotiation” to include “the negotiation of short sales of residential property.” Subsection (b) prohibits engaging in that business — or even offering to engage in it — without a license from the Department of Banking.
So then you ask, “if that’s true, how are there ‘short sale specialists’ advertising all over the place?” That is exactly the right question. The exemption list is short, and the Department of Banking publishes it right on its debt negotiator licensee page:
1. Attorneys practicing law in Connecticut. An attorney handling the negotiation as part of their law practice is exempt. Plenty of good short sales get done this way.
2. Banks and credit unions. They’re regulated separately.
3. Licensed debt adjusters. A different license, separately issued.
4. Nonprofits. Housing counseling agencies and the like.
Read that list again. Real estate brokers are not on it. A real estate license does not cover short sale negotiation in Connecticut. I hold broker licenses in three states, and none of them is the reason I’m allowed to negotiate your seller’s file — the debt negotiation license is.
“Okay, but it’s not my license on the line. Why do I care?”
Because the federal government thought of you too.
The MARS Rule — the FTC’s Mortgage Assistance Relief Services rule, now 12 CFR Part 1015 — has an assisting-and-facilitating provision at Section 1015.6. It reaches anyone who provides substantial assistance to a provider when they know, or consciously avoid knowing, that the provider is violating the rule. And the FTC’s own compliance guidance names supplying leads and referrals as an example of substantial assistance.
In plain English: the referral is the exposure. The agent who hands a homeowner to an unlicensed negotiator isn’t a bystander — they’re the one who made the introduction.
I’m not telling you who to work with, and I’m not going to name names. I’m telling you the list is public and the check takes ninety seconds on NMLS Consumer Access. If the negotiator isn’t licensed and doesn’t fit one of those four exemptions, ask them why not — then ask your broker or a real estate attorney what it means for you.
Why does the license exist in the first place?
Follow the incentives, because that’s what this law is really about. A homeowner in default is about the easiest person in the world to take advantage of. So the state wants somebody on the hook. The license comes with:
1. A surety bond. There’s money behind the license if something goes wrong.
2. An application and fitness review. The state looked at who’s running the company before saying yes.
3. A hard cap on fees charged to the homeowner — collectible only after all the contracted work is finished. Nobody licensed is taking an upfront fee from your seller.
What it buys you, the agent, is simpler: one settlement statement, with the same numbers going to every lienholder on the file. That’s how these files are supposed to run, and it’s the difference between a negotiation and the kind of two-sets-of-numbers arrangement that ends careers.
The takeaway
Before your seller signs anything with any short sale negotiator — me included — look them up. NMLS Consumer Access, ninety seconds. On the state’s list I appear as Accredited Home Services, LLC, which is the entity behind Loss Mit Services, license DN-828273 — the first debt negotiation license Connecticut issued after the requirement took effect in 2009.
And one more thing, so you hear it from me instead of at the closing table: lenders on these files sometimes require a commission reduction. That negotiation is part of the deal, not a surprise at the end.
If you’re sitting on a listing that smells like a short sale, send me the address and the approximate payoff. I’ll tell you within a day whether it’s worth pursuing.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
“Will I Ever Be Able to Buy Again?” — The Honest Answer After a Short Sale
Posted on 23. Aug, 2026 by ctlms in Blog, Foreclosures, My Blog, News, Real Estate, Short Sale, foreclosure
I get this question from sellers all the time: "If I do a short sale, will I ever be able to buy a house again?" And I get it from agents almost as often, usually phrased as "what do I tell them?"
Here's the honest answer, current as of August 2026. And I do mean current — most of the numbers floating around the short sale world are left over from the 2008 playbook, and repeating them today is how agents lose credibility at the listing table. I re-verified every figure below before writing this.
## The waiting periods, loan type by loan type
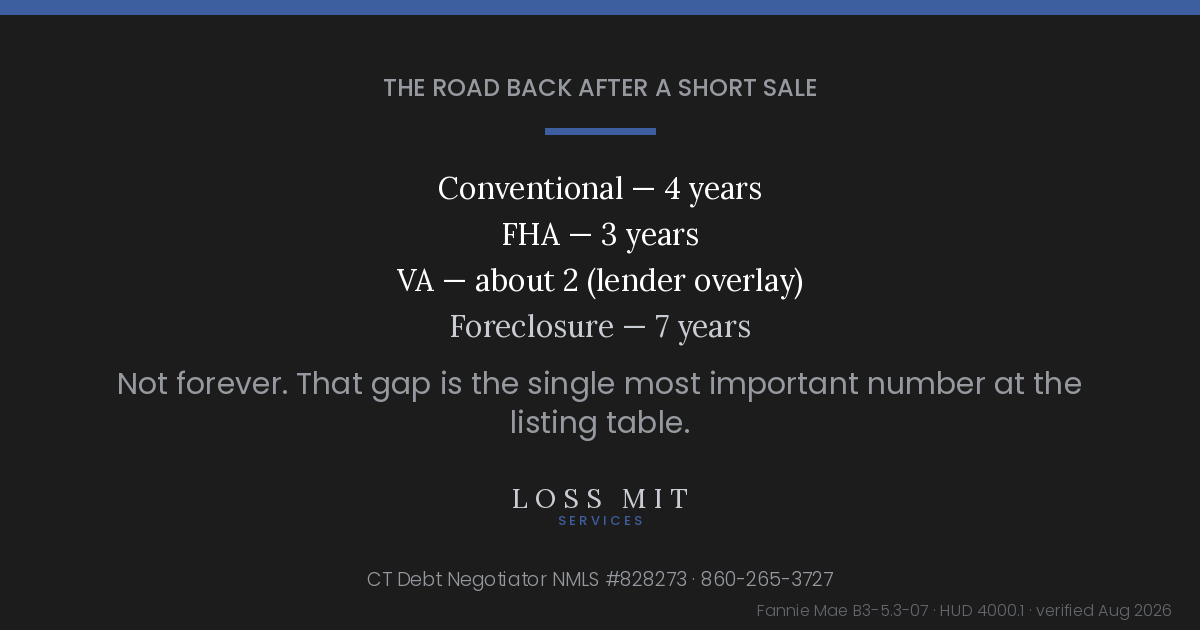
1. **Conventional (Fannie Mae): four years** after a short sale or deed-in-lieu, measured from the completion date. Two years if documented extenuating circumstances — a job loss, a medical event, a divorce — caused the default. After a foreclosure? Seven years, or three with extenuating circumstances plus added restrictions.
That four-versus-seven gap is the single most important number on this page. It's the difference a short sale actually makes.
2. **FHA: three years** after either a short sale or a foreclosure. But here's a detail almost nobody brings up: a borrower who was current on their mortgage and installment debt at the time of the short sale can potentially qualify for a new FHA loan with NO waiting period at all. Late payments in the preceding twelve months generally kill that exception — but it exists, and it's worth knowing before your seller misses a payment they didn't have to miss.
3. **VA: no published mandatory wait** after a short sale. Most lenders apply roughly two years as their own overlay, and a foreclosure carries a two-year VA wait. So which lender your buyer talks to matters — the overlay is the lender's rule, not the VA's.
## Now the part the short sale ads won't tell you
Two honesty notes, because this is where short sale marketing usually goes sideways.
**First, the credit hit.** A short sale that reports a deficiency balance scores much like a foreclosure. So then you ask, "then what's the point?" The point is the table above. The real advantage of a short sale isn't a softer credit hit — it's the faster road back to a mortgage. Four years instead of seven on conventional. Potentially zero instead of three on FHA. Anyone who tells a seller "a short sale won't hurt your credit" is setting them up, and probably setting you up too.
**Second, these are the seller's numbers to confirm.** Guidelines change. Every figure on this page comes straight from the current Fannie Mae Selling Guide and HUD Handbook 4000.1, and your buyer still needs to confirm their specific situation with a loan officer at application time. I re-verified these before posting, and you should too before you repeat them.
## Why this matters at the listing table
Follow the seller's thinking, because it explains a pattern you've probably seen. A homeowner who believes a short sale ends their homeownership forever has no reason to act. So they do nothing. And nothing usually means foreclosure — the outcome with the seven-year wait, the worse exit, and none of the control.
Showing that seller the actual road back, in writing, is often the conversation that gets a distressed listing moving. Not pressure. Not a pitch. A table with three loan types on it and a date they can circle on a calendar.
## The takeaway
If a seller asks you "will I ever buy again," the honest answer is: yes, and probably sooner than you think — four years conventional, three FHA (sometimes zero), about two VA — but confirm your specifics with a loan officer, because the guidelines move.
I've been negotiating short sales in Connecticut since 2007 — more than 2,000 closed files — and we have this conversation with sellers every week. If you're sitting with one weighing this decision, send me the address and the approximate payoff. I'll tell you within a day whether it's worth pursuing.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Connect with Us


Bio
Sean Wilder started in the pre-foreclosure business in 2007. Previously he enjoyed successbusiness in the transportation industry, real estate investing and as a licensed Realtor. Sean brought the same determination and work ethic that lead to great success in his previous businesses to Loss Mit Services based in East Windsor, CT. His focus, combined with his drive to succeed, have been essential to his success as one of the area's top short sale negotiators.
Known for finding creative ways to overcome hurdles and never ending persistence; Sean, believes in the power of team. Sean and his team are in the trenches everyday, plowing through challenges and objections while negotiating with various lenders, and finding solutions to difficult problems. It is this daily experience that brings Loss Mit Services consistent success and provides them the knowledge to share.
Sean belongs to a number of industry groups and associations that allow him to collaborate, share, learn, teach and stay updated on the latest changes in the pre-foreclosure industry at the federal, state, local and lender specific levels.
Effective Oct 1, 2009 all debt negotiation companies that offer loan modification, short sale, or foreclosure rescue services needed to be licensed by the CT Dept of Banking. Sean and his company Loss Mit Services were the 1st to be awarded the Debt Negotiation License NMLS # 828273 which can be verified at the CT Dept of Banking Website by Clicking Here. In addition, effective Oct 1, 2011 Debt Negotiators were required to also be licensed Mortgage Loan originators and Sean also has received this license, NMLS# LO-831853.

Recent Comments